MUMBAI – Kazakhstan is moving toward expanding its domestic QR-payment infrastructure across borders, with India among 11 countries identified for potential cross-border QR-payment cooperation. The initiative comes as cashless payments continue to account for the overwhelming majority of transactions in Kazakhstan.
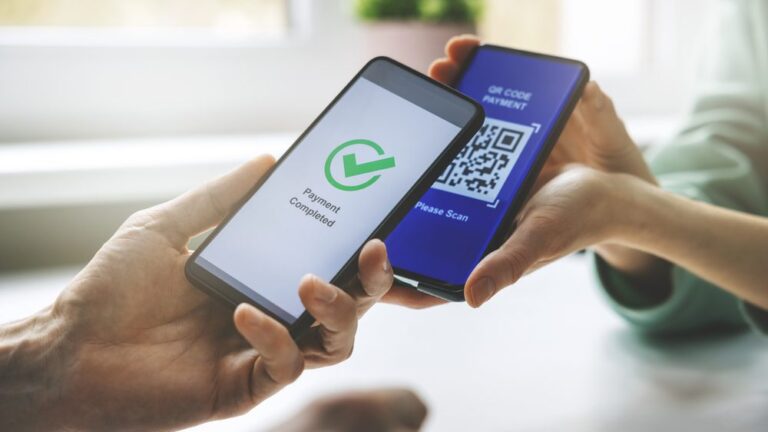
Photo credit: Shutterstock
According to the National Bank of Kazakhstan, 84 million payment cards were in circulation as of Aug. 1, with debit cards accounting for 81.6% and credit cards for 15.5%. In July, transactions using cards issued by Kazakh banks reached 19.9 trillion tenge (US$44.4 billion), covering 1.3 billion transactions.
Non-cash transactions accounted for 17.6 trillion tenge (US$39.3 billion) and 1.3 billion transactions, increasing 8.4% in value and 7.5% in number compared with July 2025. Internet and mobile banking comprise 77.6% of the number and 89.6% of the value of non-cash payments and money transfers, while POS terminals accounted for 21.9% and 10%, respectively.
The figures provide a growing domestic base for Kazakhstan’s efforts to make QR payments interoperable across borders.
Kazakhstan launched its national Interbank Mobile-Payment System on July 19, allowing customers of participating banks to make real-time interbank transfers and payments using phone numbers and a single QR code. The system enables merchants to accept payments from customers of various participating banks without installing new equipment.
The next step is to make such payments work across borders.
India’s UPI model
India offers one example of how a nationally interoperable payment infrastructure can evolve into a cross-border service.
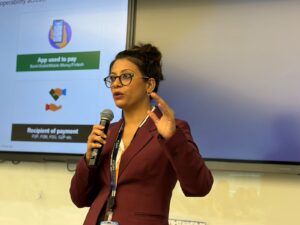
Sonal Asnani, head of Asia Pacific at NPCI International Payments Limited (NIPL). Photo credit: The Astana Times
Speaking to foreign journalists in Mumbai on Sept. 16, Sonal Asnani, head of Asia Pacific at NPCI International Payments Limited (NIPL), outlined how India developed the Unified Payments Interface (UPI) from a domestic payment infrastructure into a system with international applications.
UPI, operated by the National Payments Corporation of India (NPCI), is a payment infrastructure rather than a standalone application or card. It connects banks, fintech companies and customers through a common framework, allowing users to make payments through different applications while maintaining interoperability.
“It’s not an application, it’s not a card. It’s a payment layer,” Asnani said, explaining the basic architecture of UPI.
According to Asnani, one of the key factors behind UPI’s expansion has been the division of roles across the ecosystem. The Reserve Bank of India acts as the regulator, NPCI operates the national payment infrastructure and establishes standards, banks hold customers’ accounts and funds, while fintech companies develop customer-facing services.
This model has allowed users to make payments through various applications while relying on the same underlying infrastructure.
From domestic payments to international use
NPCI created NIPL in 2020 to take Indian payment technologies and expertise to international markets.
One of its main areas of activity is cross-border merchant payments. Under UPI Global Acceptance, Indian users can make QR-based payments at participating international merchants directly from UPI-enabled applications.
Asnani noted that users can scan a participating local QR code and review the transaction amount, exchange rate, and applicable fees before completing the payment.
She said NPCI International currently works with 11 countries on international merchant-payment acceptance.
The model allows an Indian traveler to use a familiar UPI-enabled application abroad rather than relying exclusively on cash or international payment cards.
“For example, when I travel to other countries, I can scan the local QR with my UPI app and still make a payment,” Asnani said.
For Kazakhstan, which is developing cross-border QR arrangements with India and other countries, interoperability could provide a similar mechanism for travelers and merchants.
The practical question, however, is how two national payment systems can be connected while preserving their respective regulatory and technical frameworks.
Asnani highlighted that such partnerships require due diligence and compliance procedures, while the presence of an established QR-payment ecosystem in the partner country can make integration more straightforward.
“Wherever there is a high level of QR adoption, and there is a QR system, it becomes natural for us to collaborate,” she said, describing the factors considered when establishing international partnerships.
Beyond QR payments
NPCI International’s activities extend beyond merchant payments. The organization also works on cross-border person-to-person remittances and provides technology to countries seeking to develop their own domestic payment infrastructure.
Asnani said some countries have adopted elements of India’s technology to develop sovereign instant-payment or card systems rather than building such infrastructure entirely from scratch.
That approach differs from simply connecting two existing payment systems. It involves sharing technological infrastructure and experience with countries that are developing or upgrading their own national payment systems.
Kazakhstan has a well-developed digital payments ecosystem. The next step is to connect its existing infrastructure with international payment networks while ensuring seamless interoperability and maintaining regulatory oversight.
The potential use cases extend beyond tourism. Cross-border QR payments could facilitate transactions for travelers, small businesses and merchants. At the same time, interoperability between payment systems could also support broader economic and financial links between Kazakhstan and its partner countries.
The country’s growing domestic use of digital payments provides a substantial base for such expansion. In January-July, QR-code payments within Kazakhstan accounted for 2.34 billion transactions worth 11.8 trillion tenge (US$26.3 billion), according to National Bank data.
As Kazakhstan moves from domestic QR interoperability toward international connectivity, India’s experience offers one possible path. This involves building common infrastructure, allowing banks and fintech companies to compete at the customer level, and using interoperable standards to make the payment experience seamless for users.
